Portfolio ManagementLab EN
The Attribution Lab
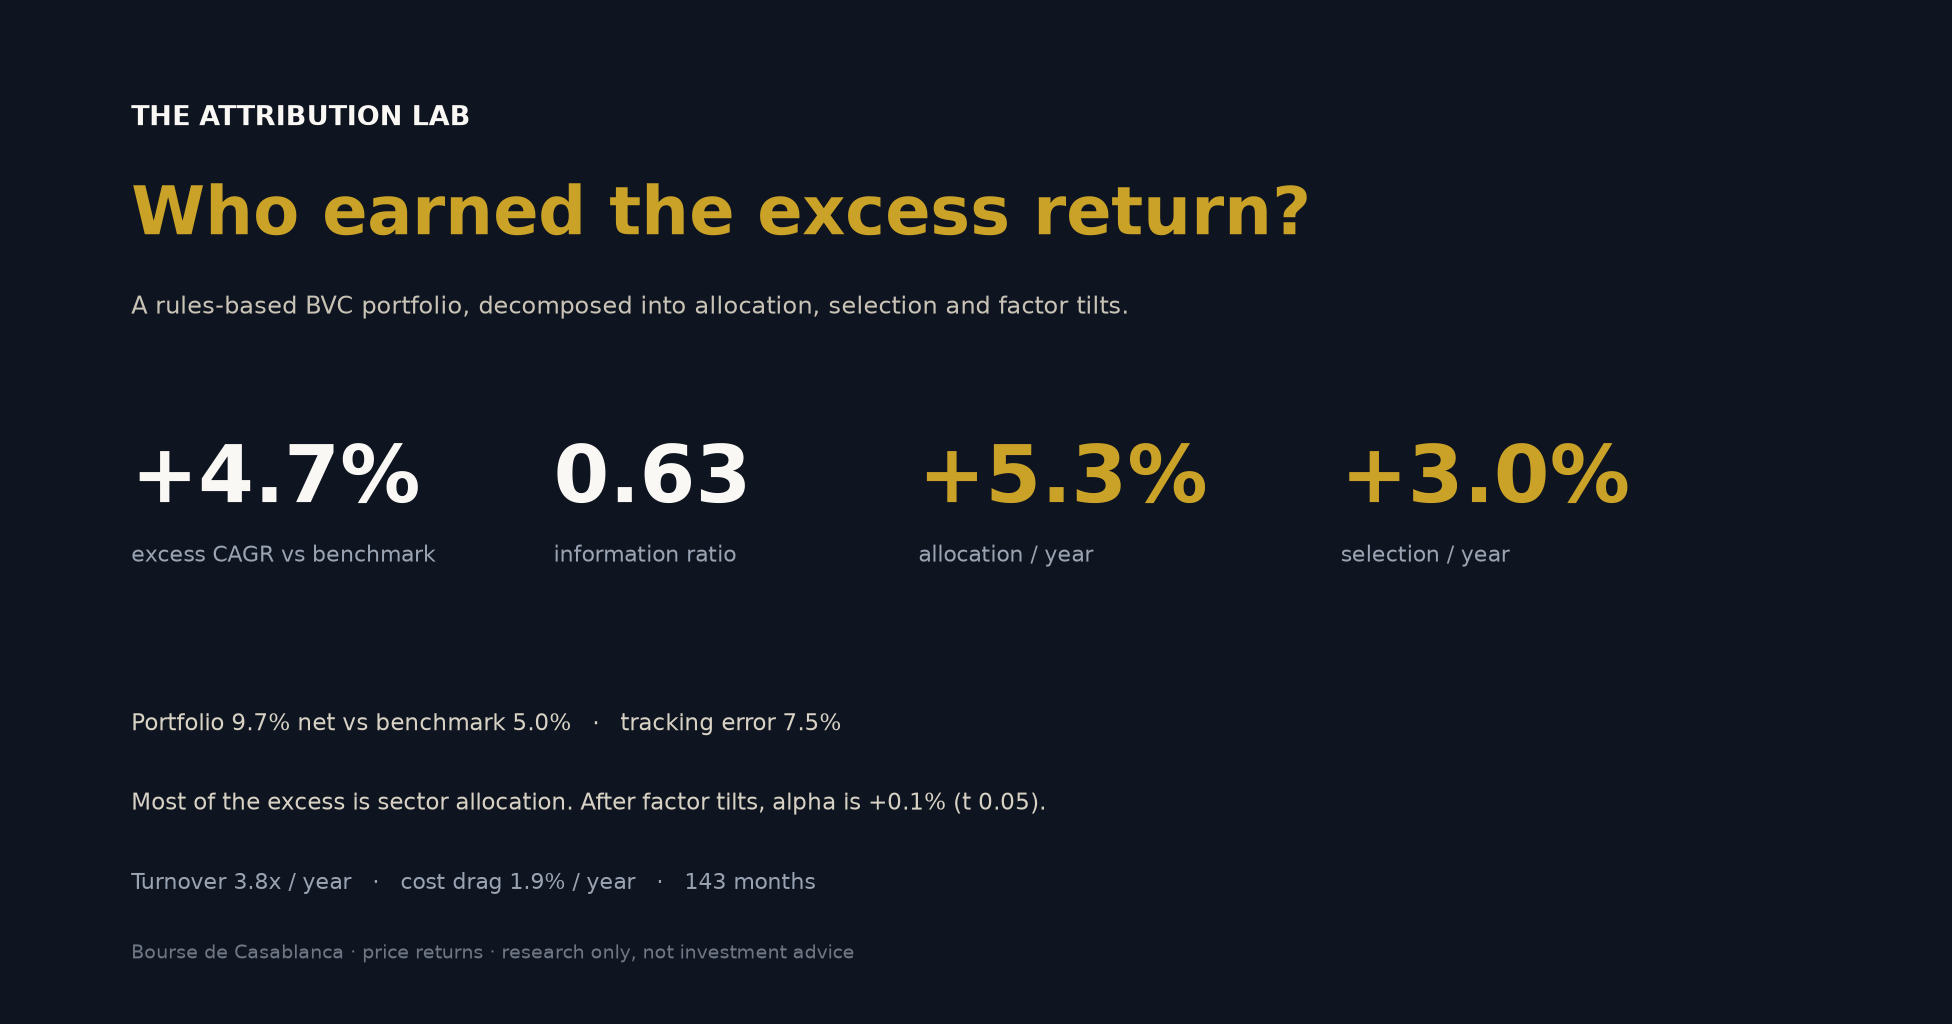
A rules-based 15-name BVC portfolio compounded at 9.7% net against a 5.0% cap-weighted benchmark, a 4.7% annual excess with a 0.63 information ratio. …
+5.3% allocation / yr
The desk · projects
Quantitative labs on real market data: performance attribution, factor research, BVC liquidity, fixed income hedging, derivatives and goal-based allocation.
Research environments built around a reproducible question: the data, the method, the result and the limits, with the working model attached.
5 projects on the desk
Portfolio ManagementLab EN
A rules-based 15-name BVC portfolio compounded at 9.7% net against a 5.0% cap-weighted benchmark, a 4.7% annual excess with a 0.63 information ratio. …
Portfolio ManagementLab EN
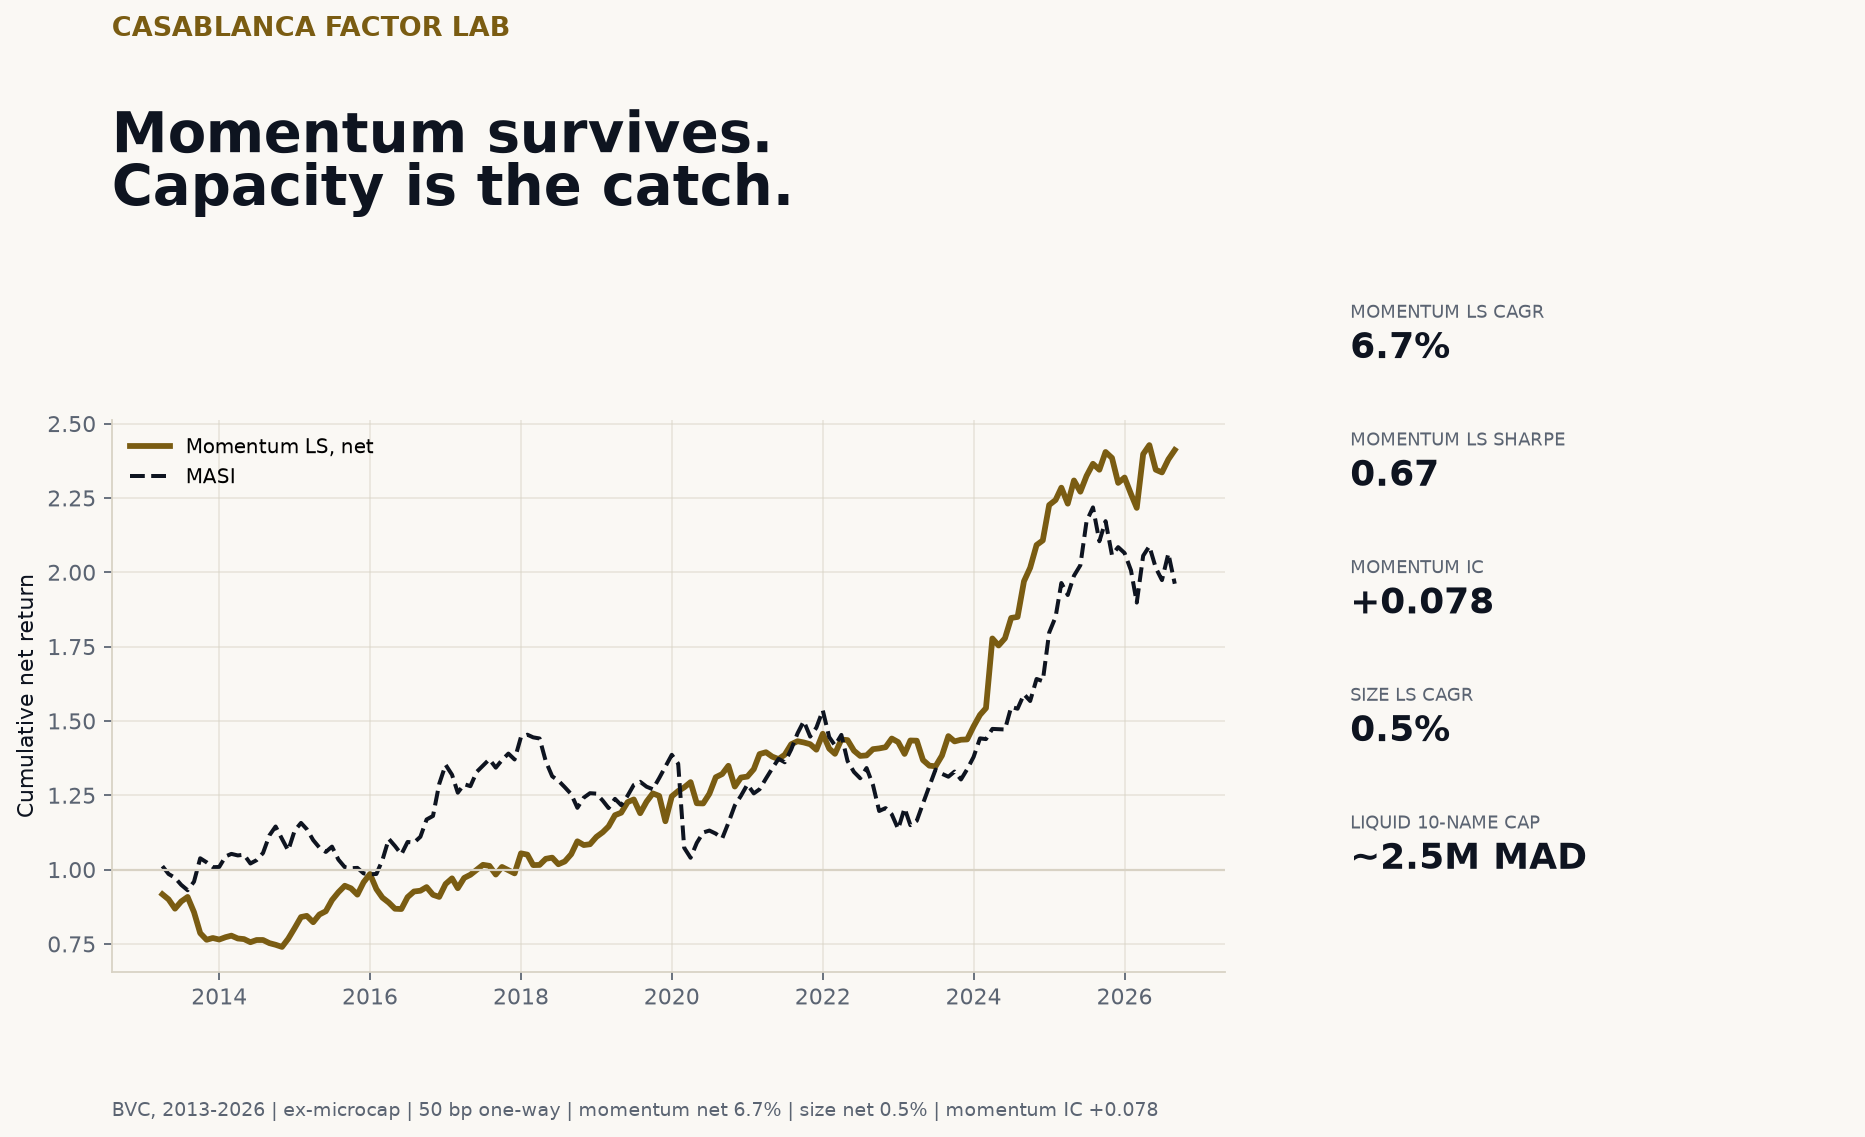
Momentum is the only factor with a positive, significant premium after excluding microcaps: 6.7% net CAGR, 0.67 Sharpe, 0.078 IC. Size earns 0.5%, the …
Portfolio ManagementLab EN
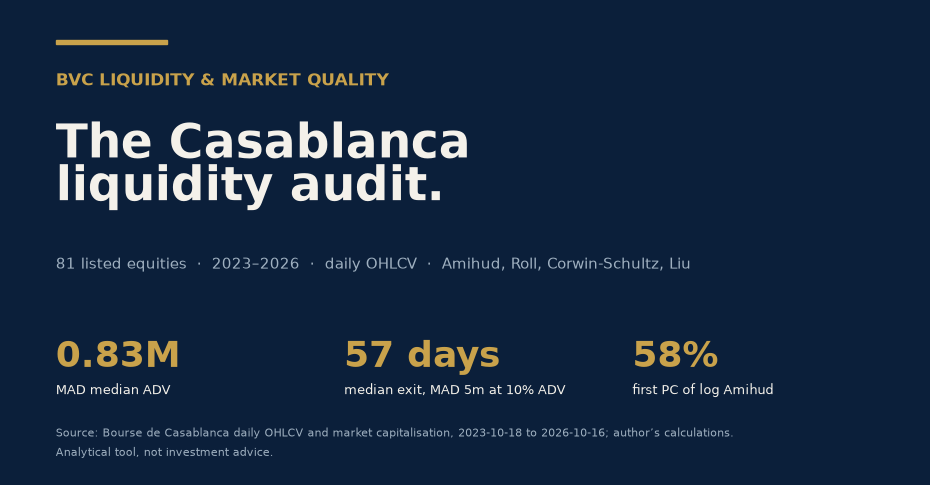
The BVC is thin. Median ADV is 0.83M MAD; the median stock needs 57 days to exit a MAD 5m position at 10% of ADV. Even ATW needs 1.3 days. 84% of names are …
Portfolio ManagementLab EN
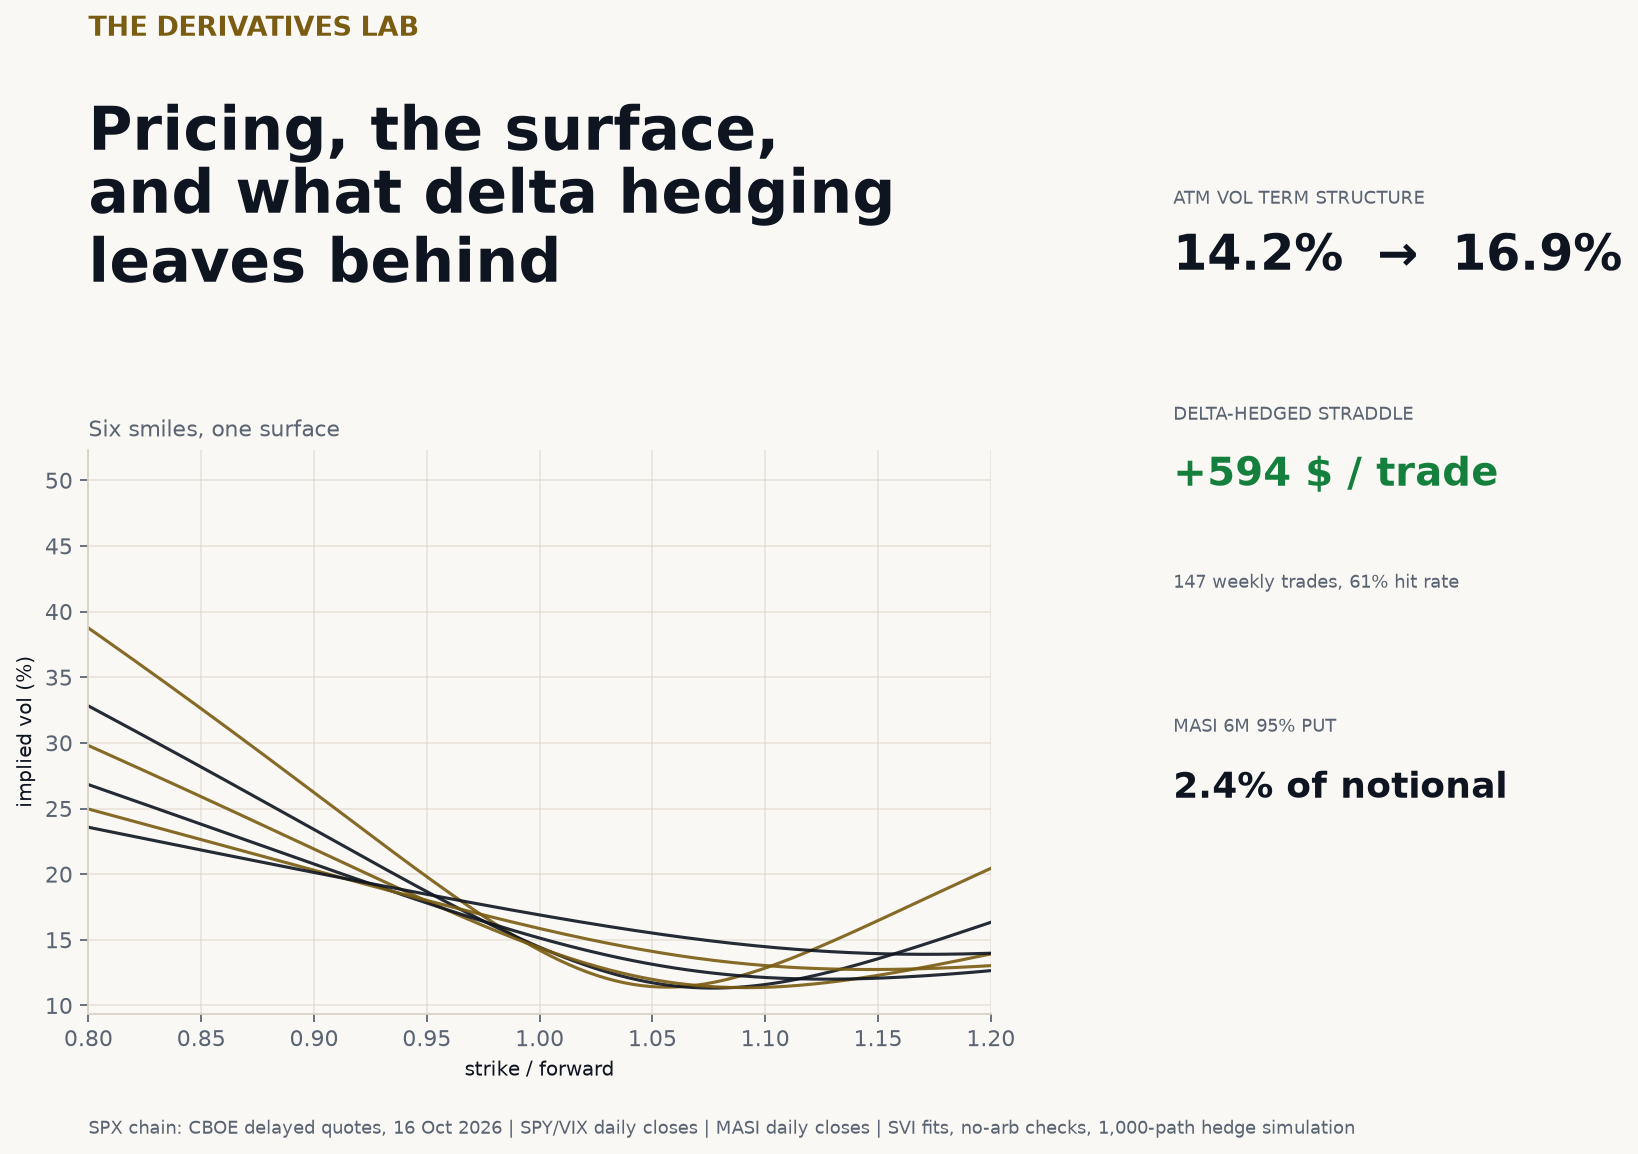
A full derivatives lab on real data: the SPX surface across six expiries (2,565 quotes, forwards from put-call parity, butterfly-constrained SVI, 0.03 …
Portfolio ManagementLab EN
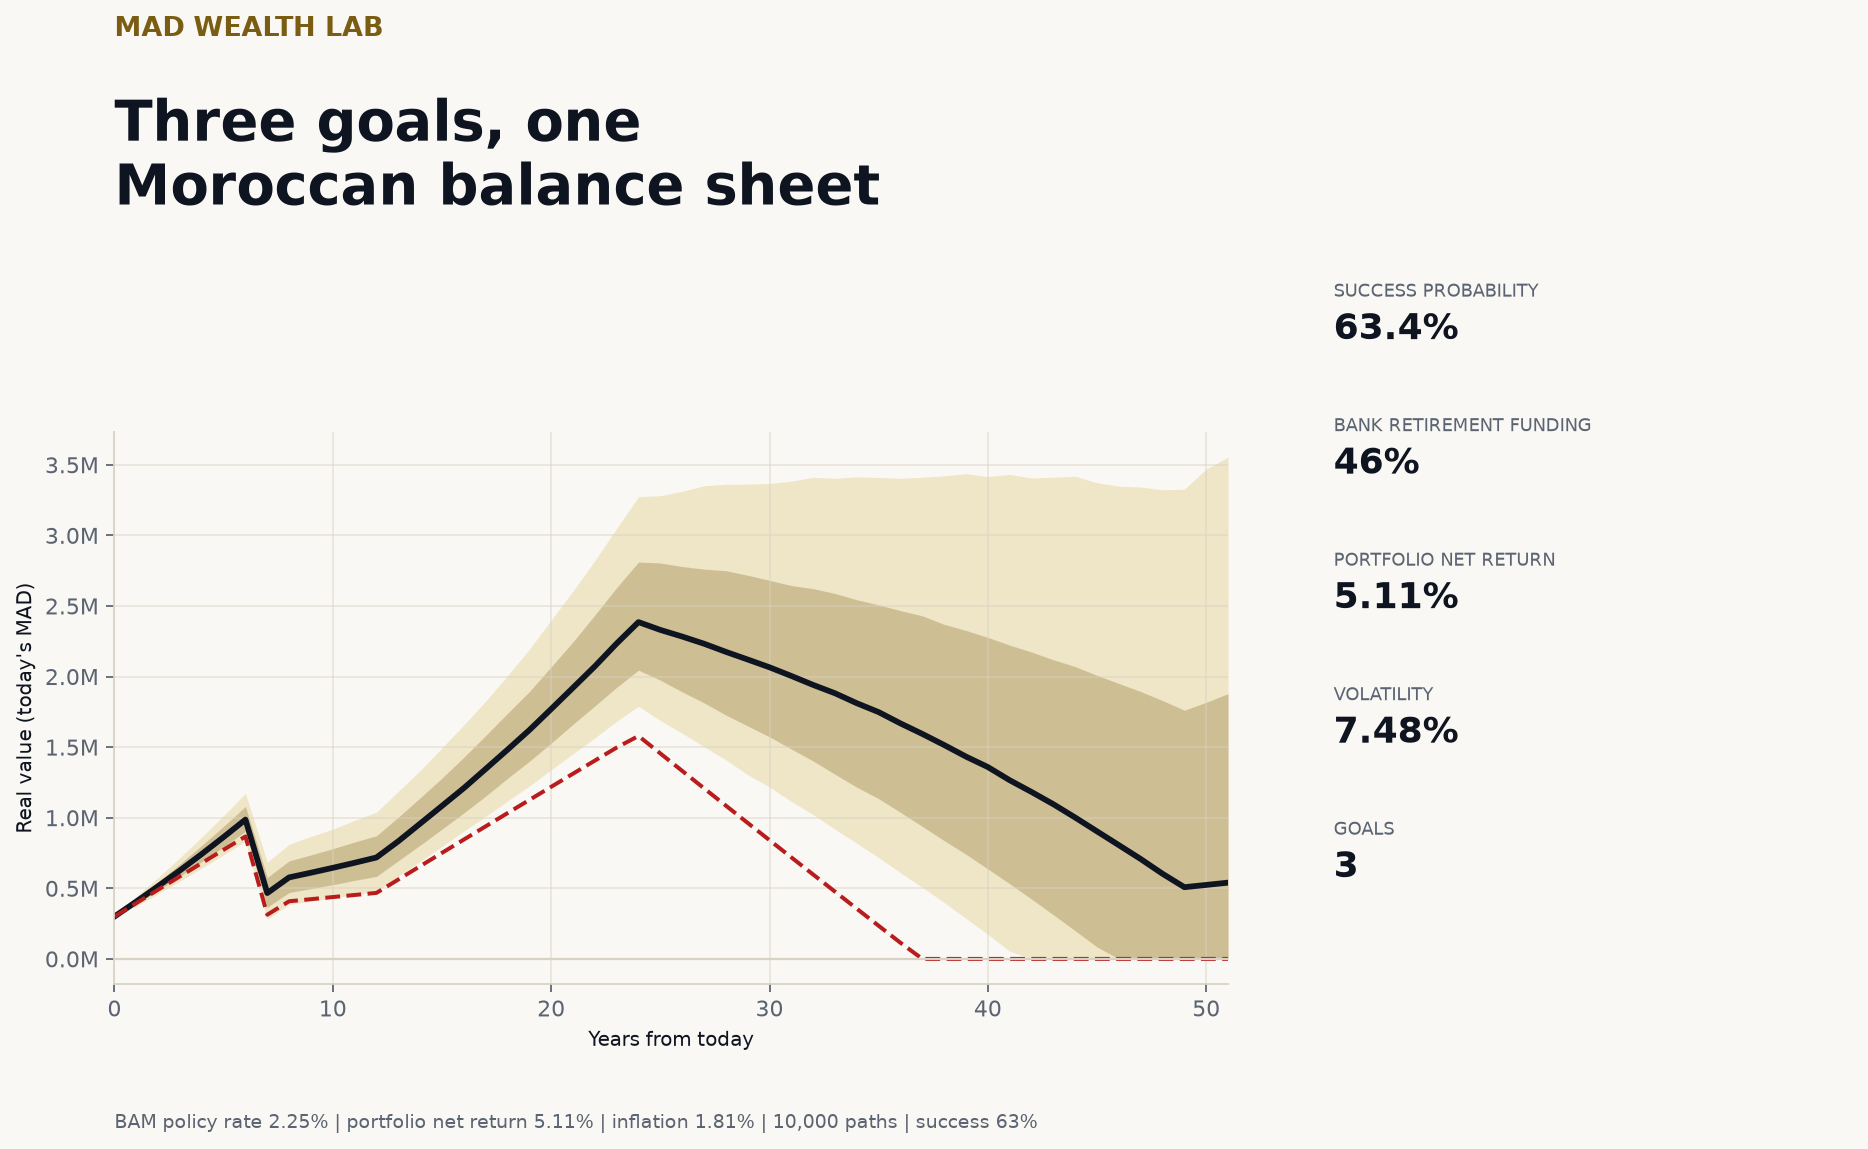
A 38-year-old household with 300,000 MAD saved and 8,000 MAD a month funds a property down payment, four years of university and retirement from one …
5 projects
Type to search across portfolio work, corporate finance, notes and pitch exercises.