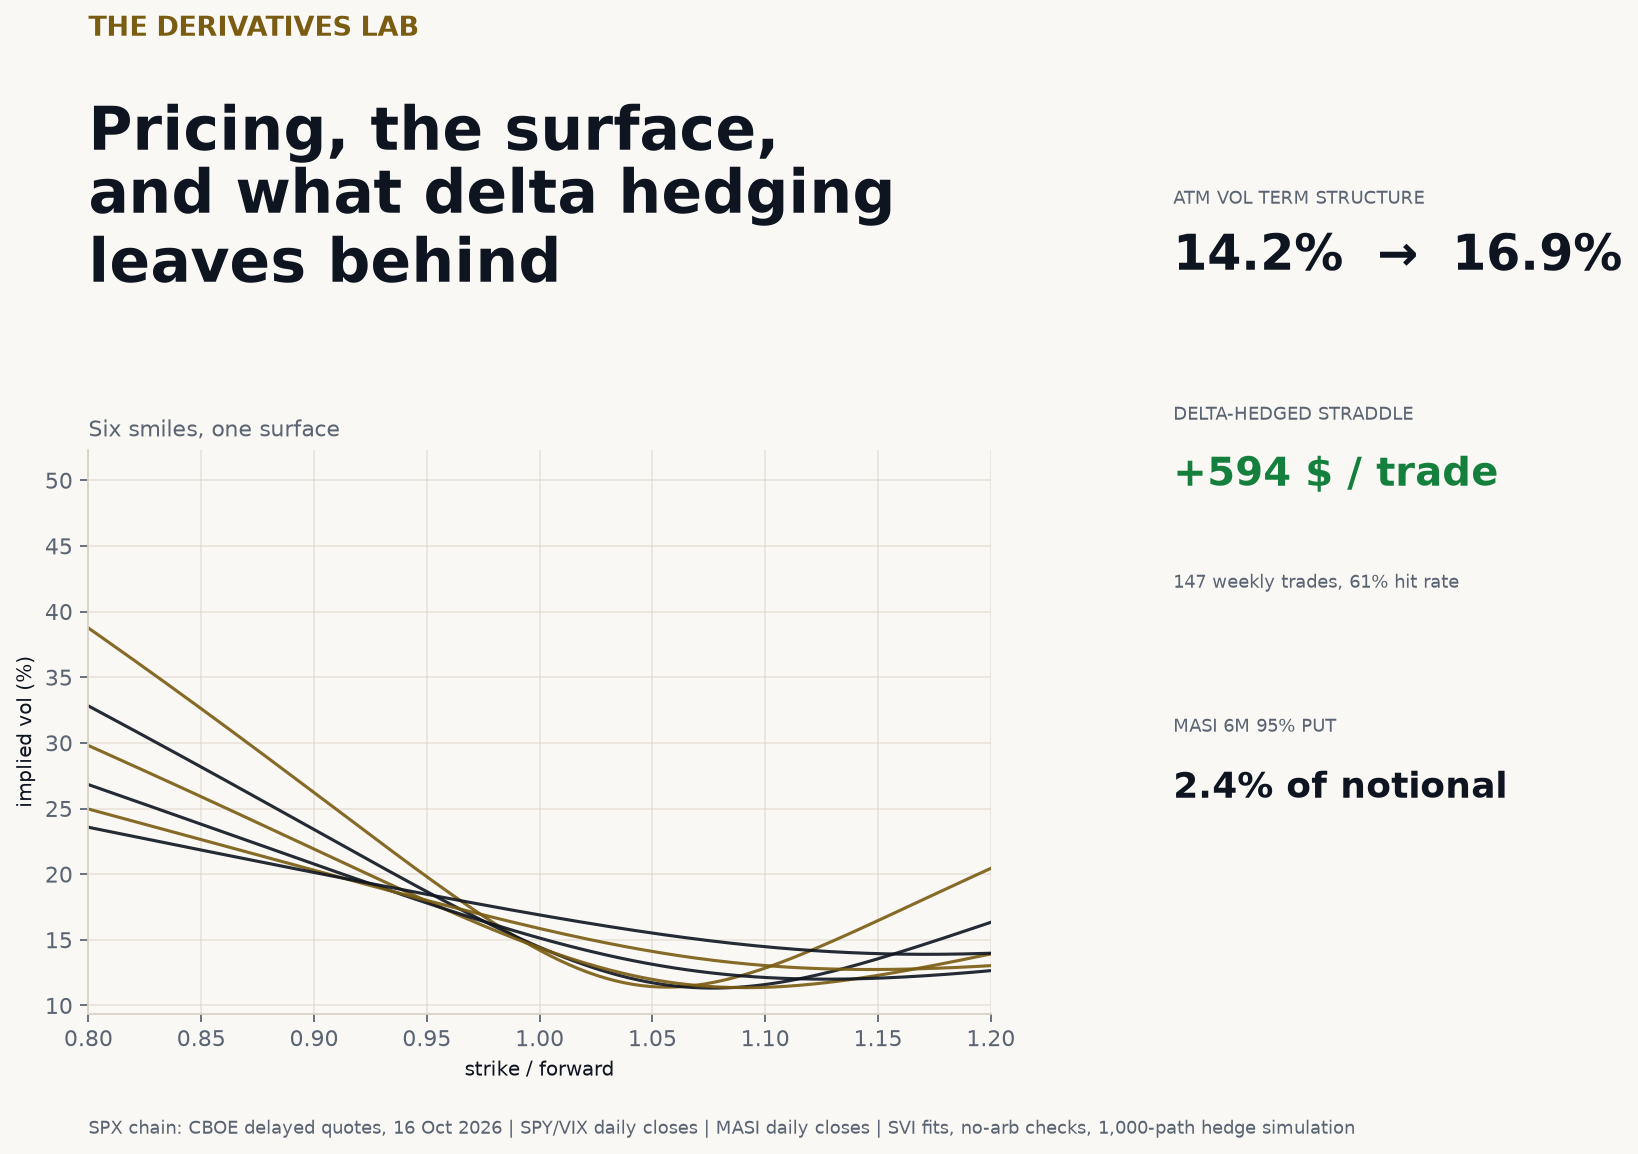
The Derivatives Lab
A full derivatives lab on real data: the SPX surface across six expiries (2,565 quotes, forwards from put-call parity, butterfly-constrained SVI, 0.03 vol-pt median cross-check against CBOE), BSM/binomial/Monte-Carlo pricing with convergence, an 85% variance cut from delta-gamma hedging, a 147-trade delta-hedged straddle check at VIX (+24.5% of premium, -$4,000 fifth-percentile tail), and a 6M 95% MASI put at 2.39% of notional.