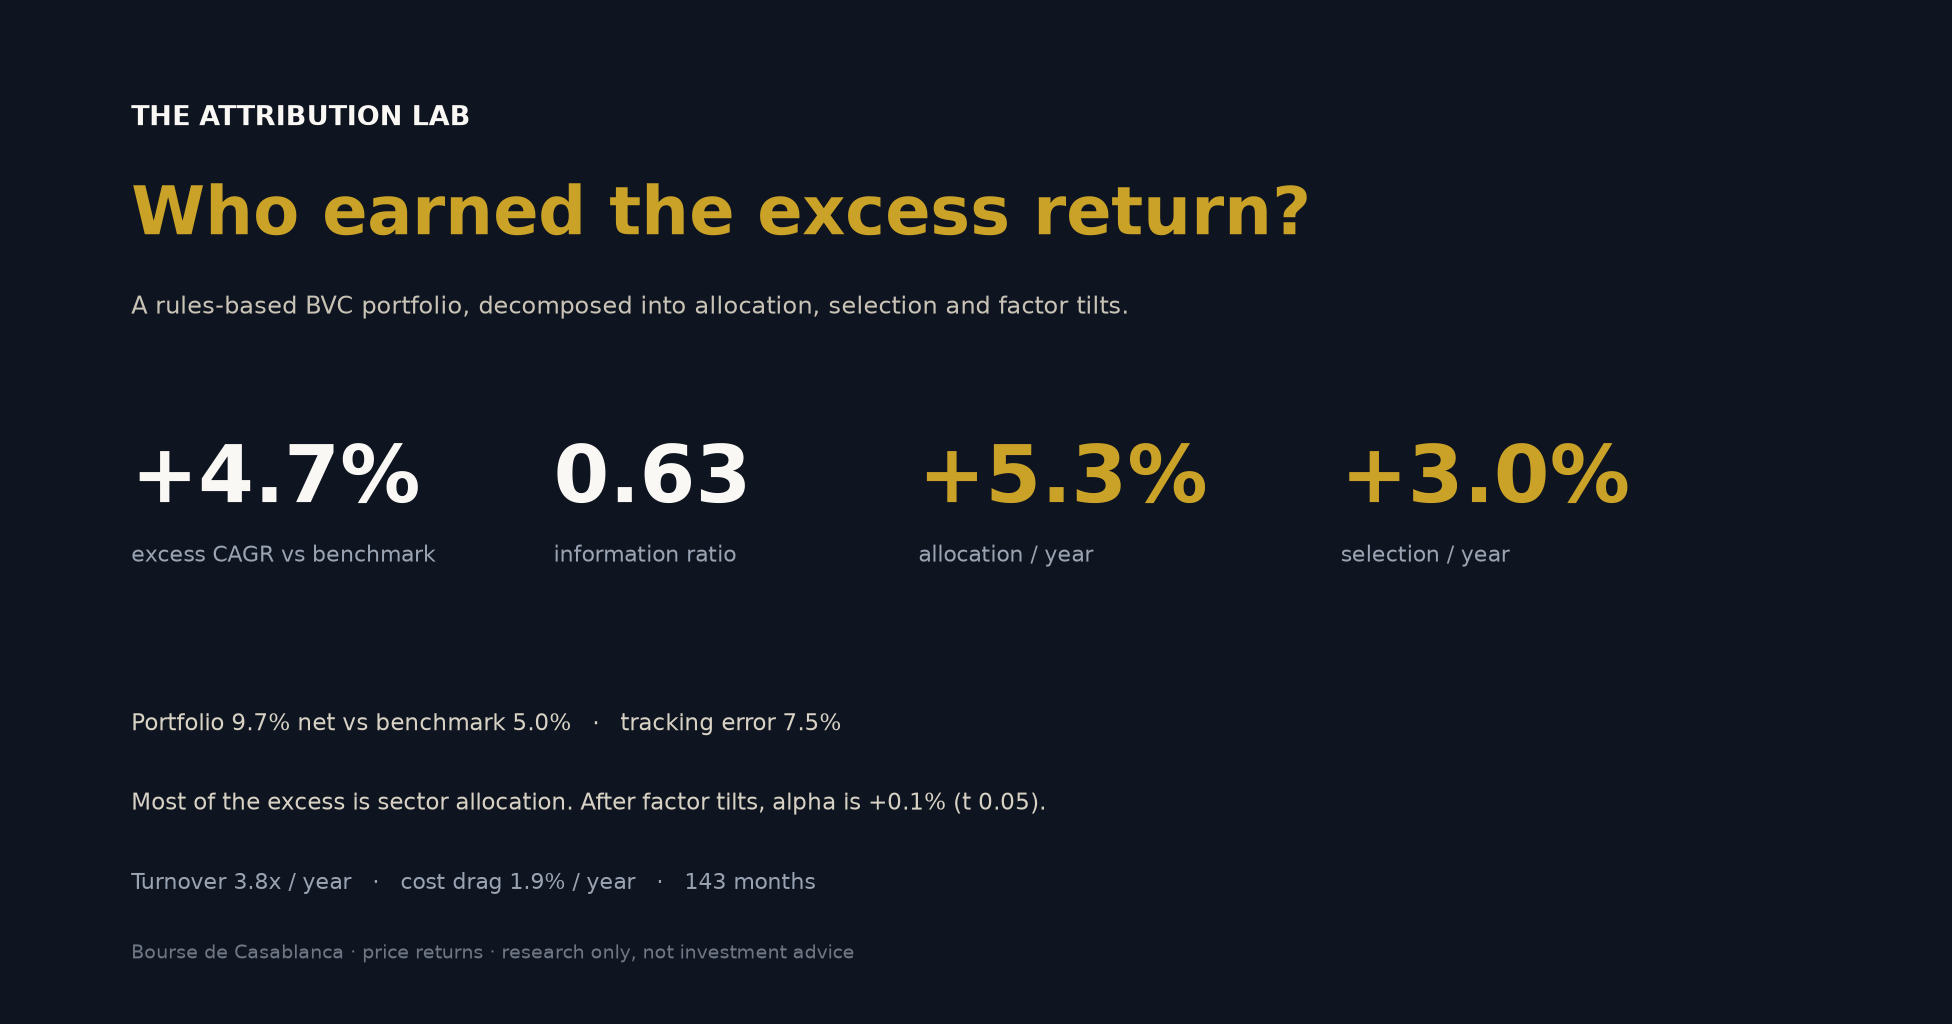
The Attribution Lab - 9.7% portfolio CAGR vs 5.0% benchmark, 0.63 information ratio, allocation +5.3% and selection +3.0% per year, alpha +0.1%

The Attribution Lab

A rules-based 15-name BVC portfolio compounded at 9.7% net against a 5.0% cap-weighted benchmark, a 4.7% annual excess with a 0.63 information ratio. Brinson-Fachler attribution puts 5.3 points on sector allocation and 3.0 on selection, while interaction (-1.7) and costs (-1.9) take back about two-fifths of the gross 8.3. A Newey-West regression on momentum, value, quality, size and low-vol leaves an alpha of +0.1% (t = 0.05). The excess is a systematic sector and factor exposure, not stock-picking skill — and 2024 alone supplies a large share of it.
EN · October 18, 2026 · Yirviel Somé
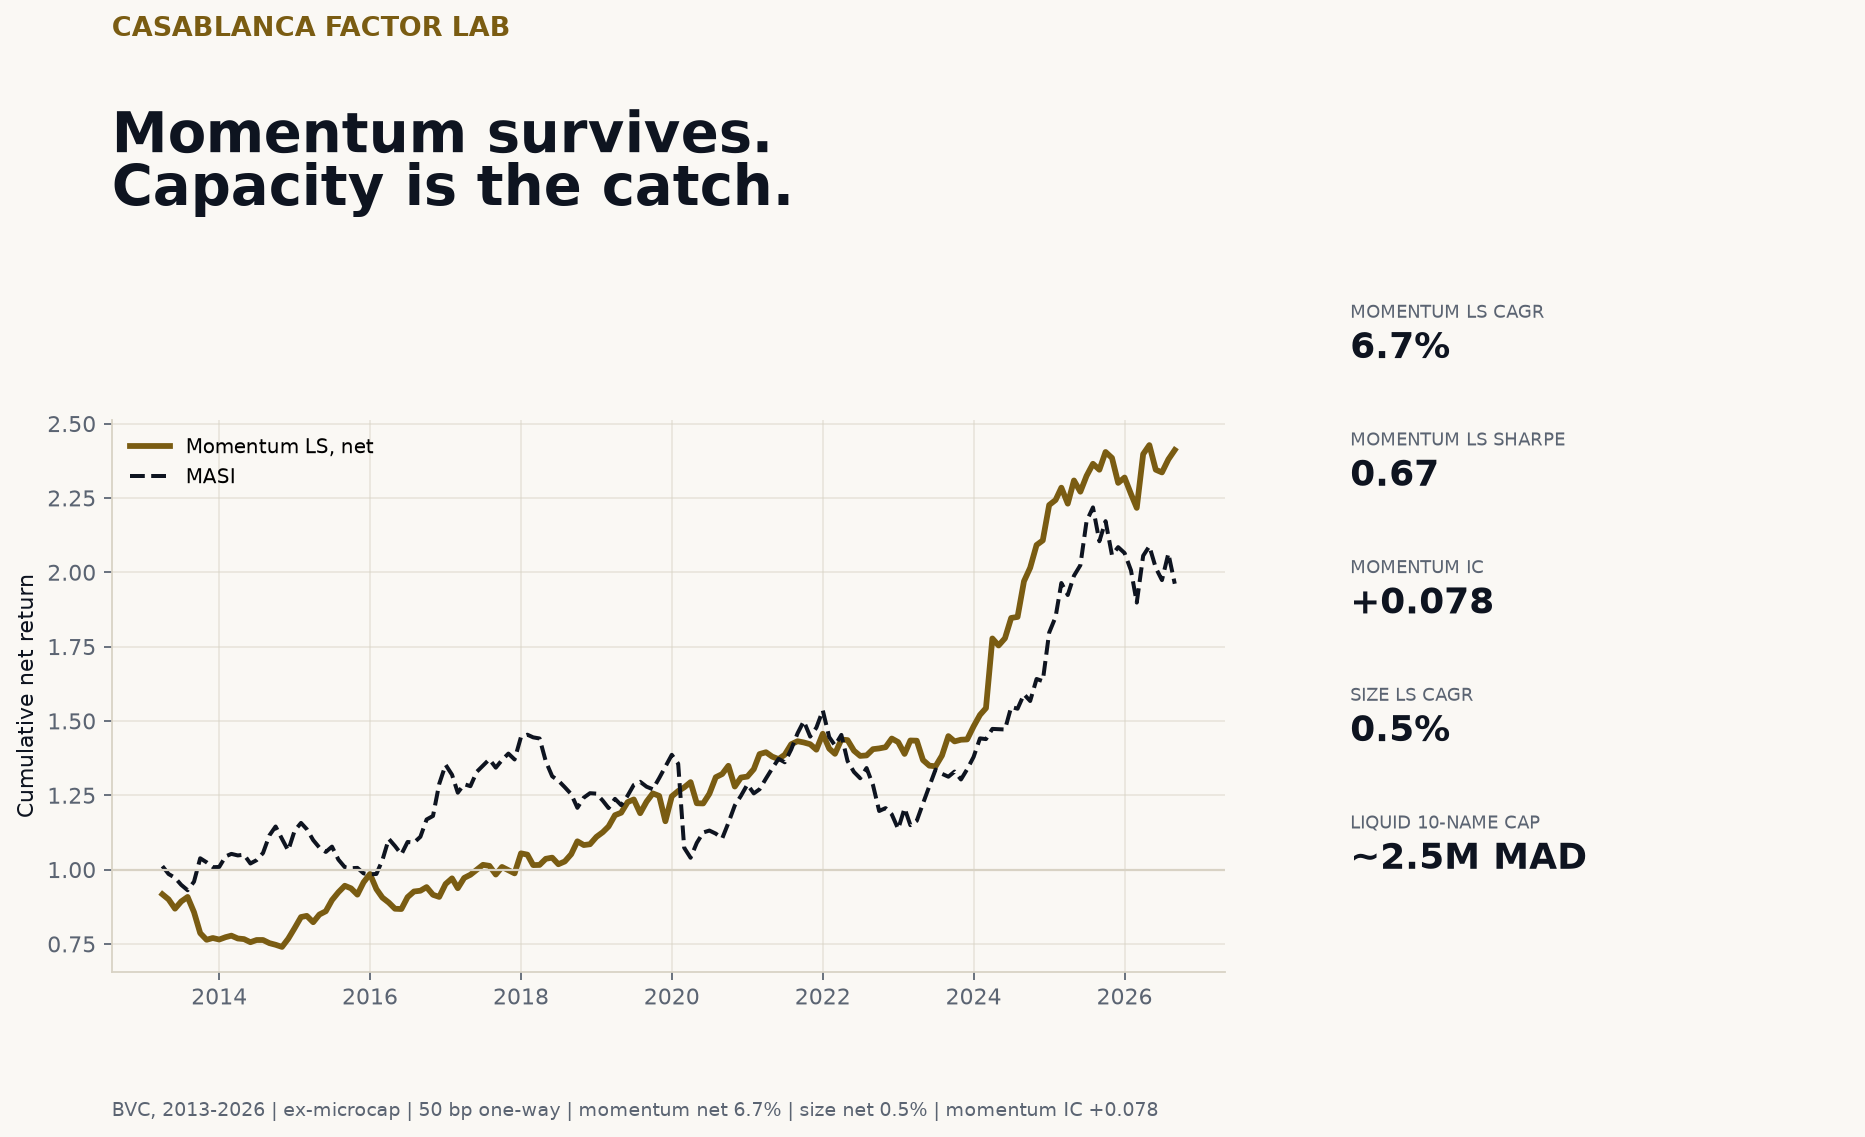
Casablanca Factor Lab - momentum 6.7% net CAGR, 0.67 Sharpe, 0.078 IC, size 0.5%, 10-name capacity about 2.5M MAD

The Casablanca Factor Lab

Momentum is the only factor with a positive, significant premium after excluding microcaps: 6.7% net CAGR, 0.67 Sharpe, 0.078 IC. Size earns 0.5%, the value proxy -5.8%, low-vol -5.9%. But a 10-name long-only implementation caps out around 2.5M MAD at 10% of ADV. The factor is real; the capacity is not.

EN · October 18, 2026 · Yirviel Somé
The BVC Liquidity Lab - 81 BVC names, 0.83M MAD median ADV, 57 days median exit for MAD 5m at 10% ADV, 58% first PC of log Amihud

The BVC Liquidity Lab

The BVC is thin. Median ADV is 0.83M MAD; the median stock needs 57 days to exit a MAD 5m position at 10% of ADV. Even ATW needs 1.3 days. 84% of names are red-flagged, 68% have a variance ratio below one, 87% show ARCH effects, and the first principal component of log Amihud explains 58% of liquidity variation. A daily-data liquidity audit, with the limits stated.

EN · October 18, 2026 · Yirviel Somé
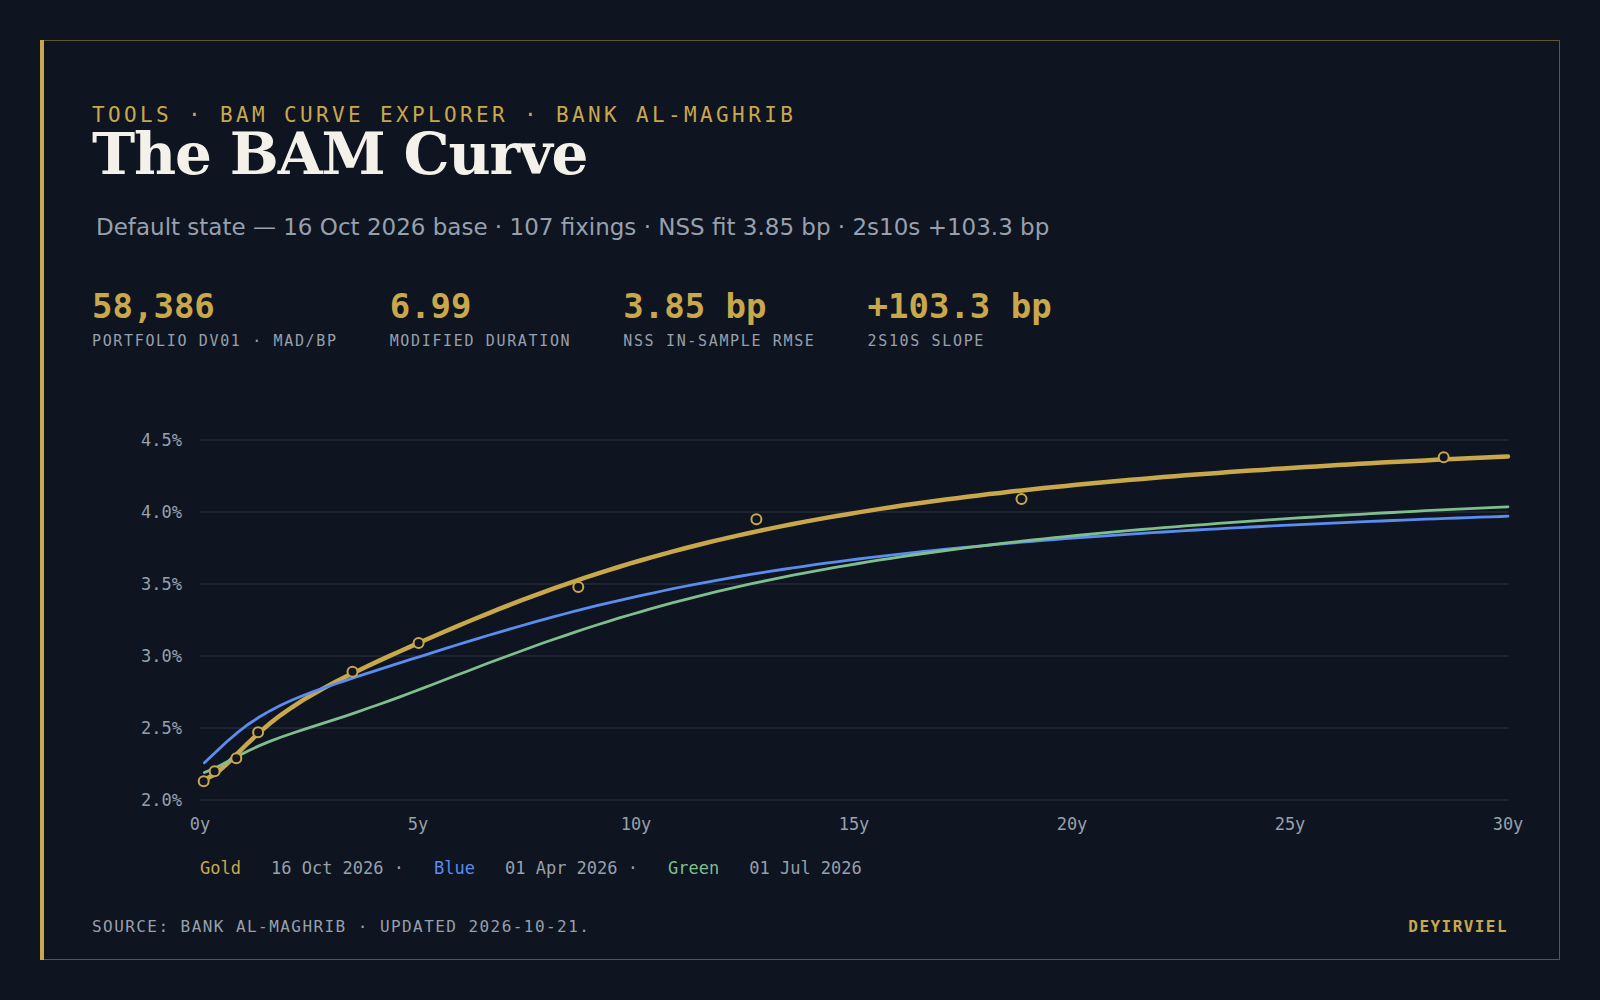
BAM Curve Explorer — fitted Bank Al-Maghrib curves for 1 April, 1 July and 16 October 2026, 58,386 MAD/bp portfolio DV01, NSS fit RMSE 3.85 bp

The BAM Curve, Priced and Hedged

Bank Al-Maghrib’s 16 October 2026 reference curve, fitted with NSS (3.85 bp in-sample, 30.6 bp leave-one-out) and used to price an 81.4M MAD sovereign book. A duration-only hedge zeroes total DV01 with a 76.9M short in the 8.7Y line, but concentrates key-rate risk at that point and leaves 3.40B of convexity. A two-instrument duration+convexity hedge zeroes both but leaves +369k to a +100 bp belly move at 12.76Y. A six-line key-rate hedge (3.5Y–28.5Y) cuts belly P&L to +86k, is 95% executable under a 10M-per-line cap, and cuts daily backtest volatility from 112k to 6k MAD. The duration-only hedge leaves 50k and still has the largest residual among the hedges.

EN · October 17, 2026 · Yirviel Somé
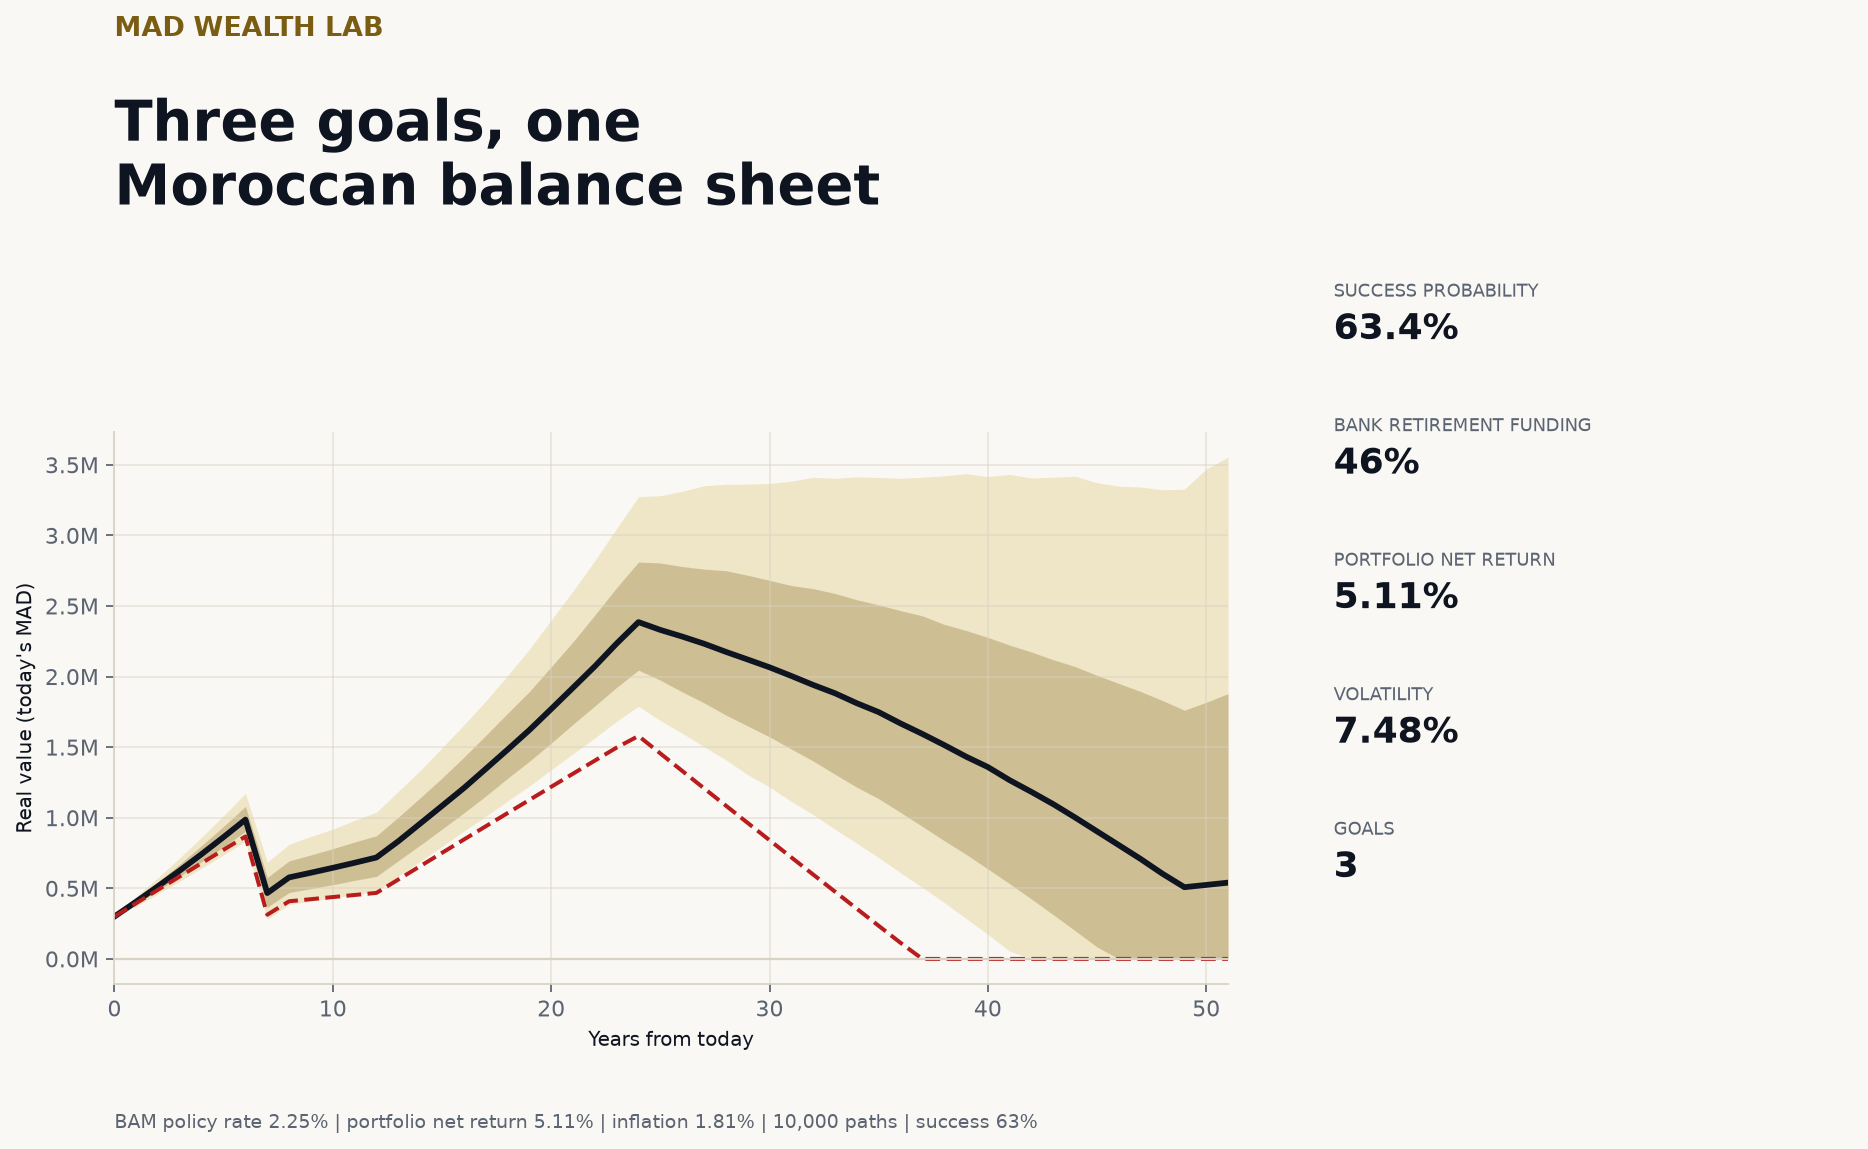
MAD Wealth Lab - three goals, one Moroccan balance sheet, 63.4% success probability, 5.11% net return, 7.48% volatility

The MAD Goal-Based Allocation Lab

A 38-year-old household with 300,000 MAD saved and 8,000 MAD a month funds a property down payment, four years of university and retirement from one portfolio. Using real BAM, BVC, gold, USD/MAD and World Bank inflation data, 10,000 monthly paths, and Moroccan tax drag from the CGI, the diversified plan succeeds 63.4% of the time. The bank deposit funds the house and the degree but only 46.5% of retirement, exhausting the portfolio around age 75. Taxes cost 16 points of success; inflation is the largest single risk.

EN · October 17, 2026 · Yirviel Somé