Risk Dashboard
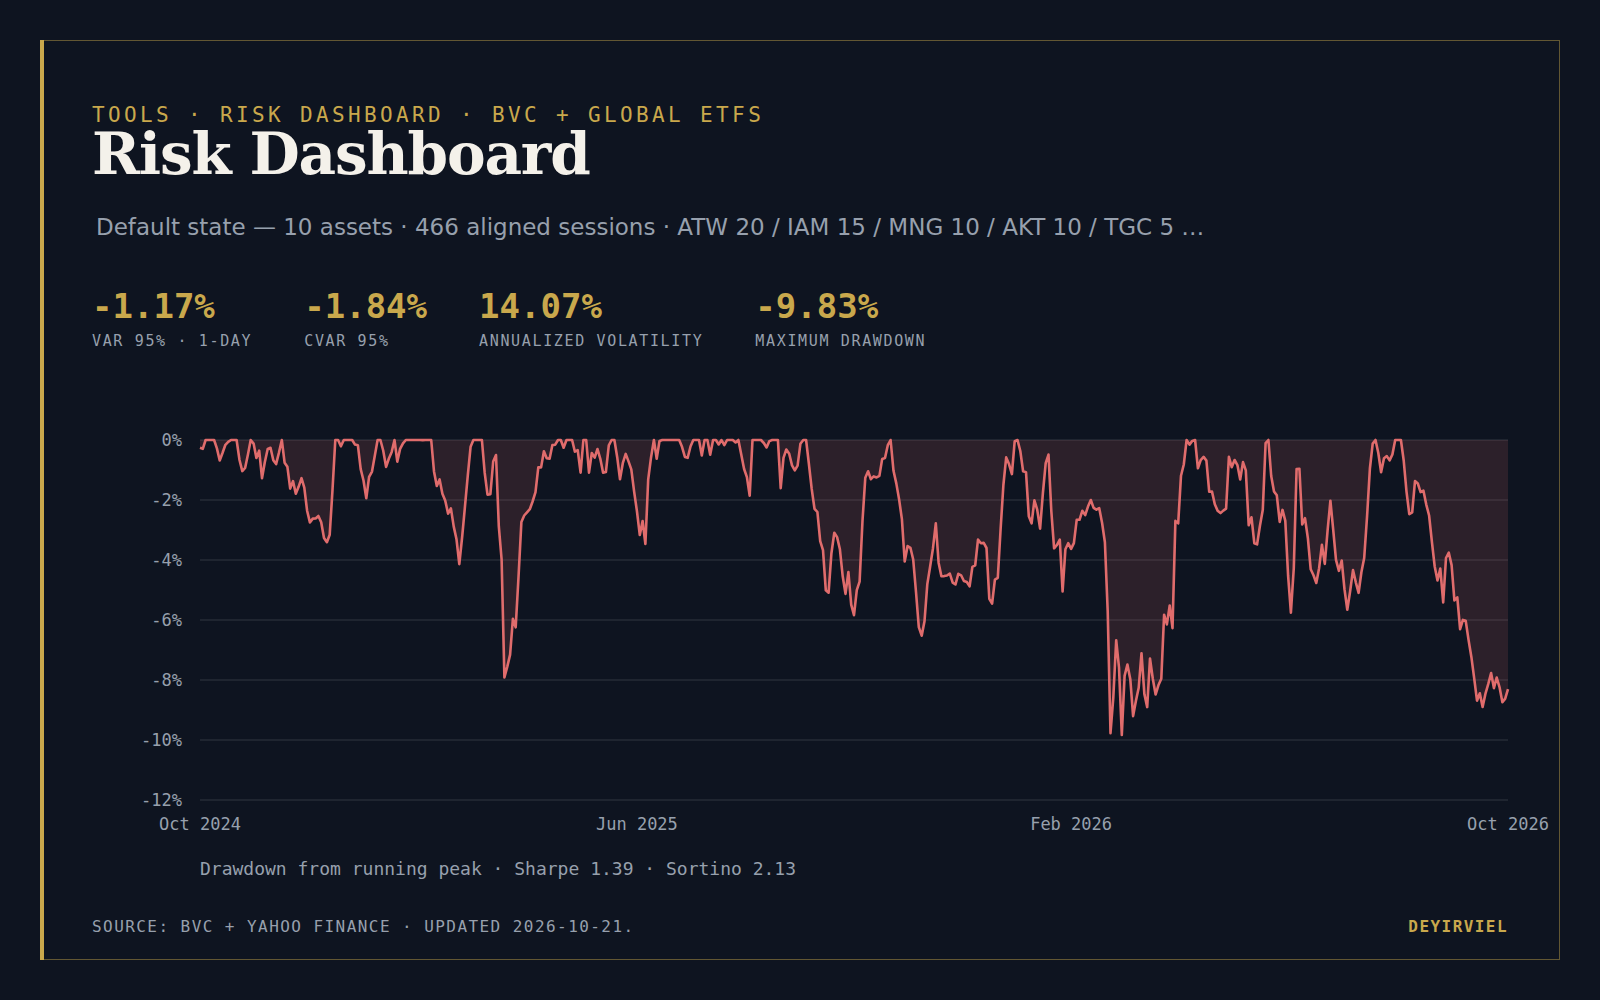
A weighted BVC and global-ETF portfolio risk dashboard: historical VaR 95%/99% and CVaR, annualized volatility, maximum drawdown, Sharpe and Sortino, rolling volatility and correlations, and deterministic equity and rate shocks.
A weighted BVC and global-ETF portfolio risk dashboard: historical VaR 95%/99% and CVaR, annualized volatility, maximum drawdown, Sharpe and Sortino, rolling volatility and correlations, and deterministic equity and rate shocks.
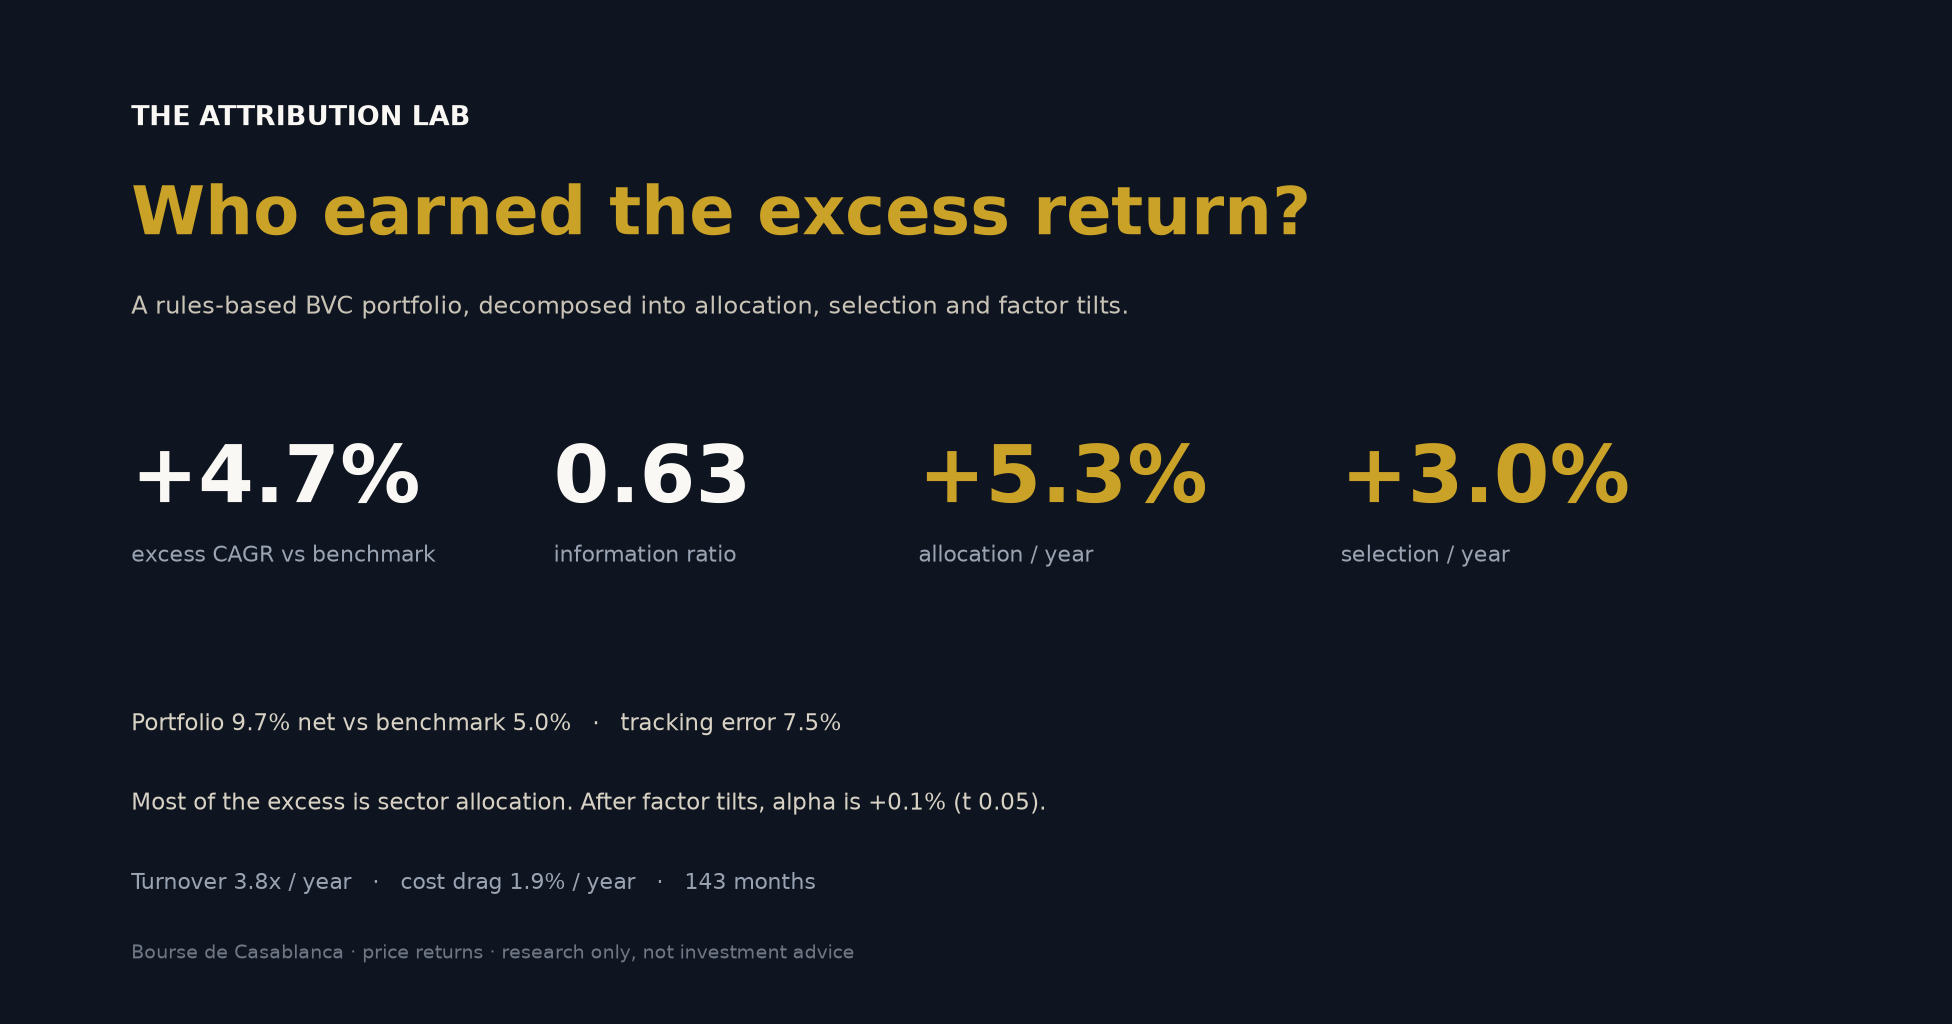
A rules-based 15-name BVC portfolio compounded at 9.7% net against a 5.0% cap-weighted benchmark, a 4.7% annual excess with a 0.63 information ratio. Brinson-Fachler attribution puts 5.3 points on sector allocation and 3.0 on selection, while interaction (-1.7) and costs (-1.9) take back about two-fifths of the gross 8.3. A Newey-West regression on momentum, value, quality, size and low-vol leaves an alpha of +0.1% (t = 0.05). The excess is a systematic sector and factor exposure, not stock-picking skill — and 2024 alone supplies a large share of it.
I finished OverTheWire Bandit last night — level 33, the last one. I expected a sense of victory. I got a README file, a blinking cursor, and a realization I have not been able to shake since: almost none of the game was actually about Linux. The password chain is a track record. A permission bit is a position limit. A setuid binary is leverage. The hard part was never the command; it was earning the right to run it — which, it turns out, is the whole job.
Type to search across portfolio work, corporate finance, notes and pitch exercises.