The Attribution Lab
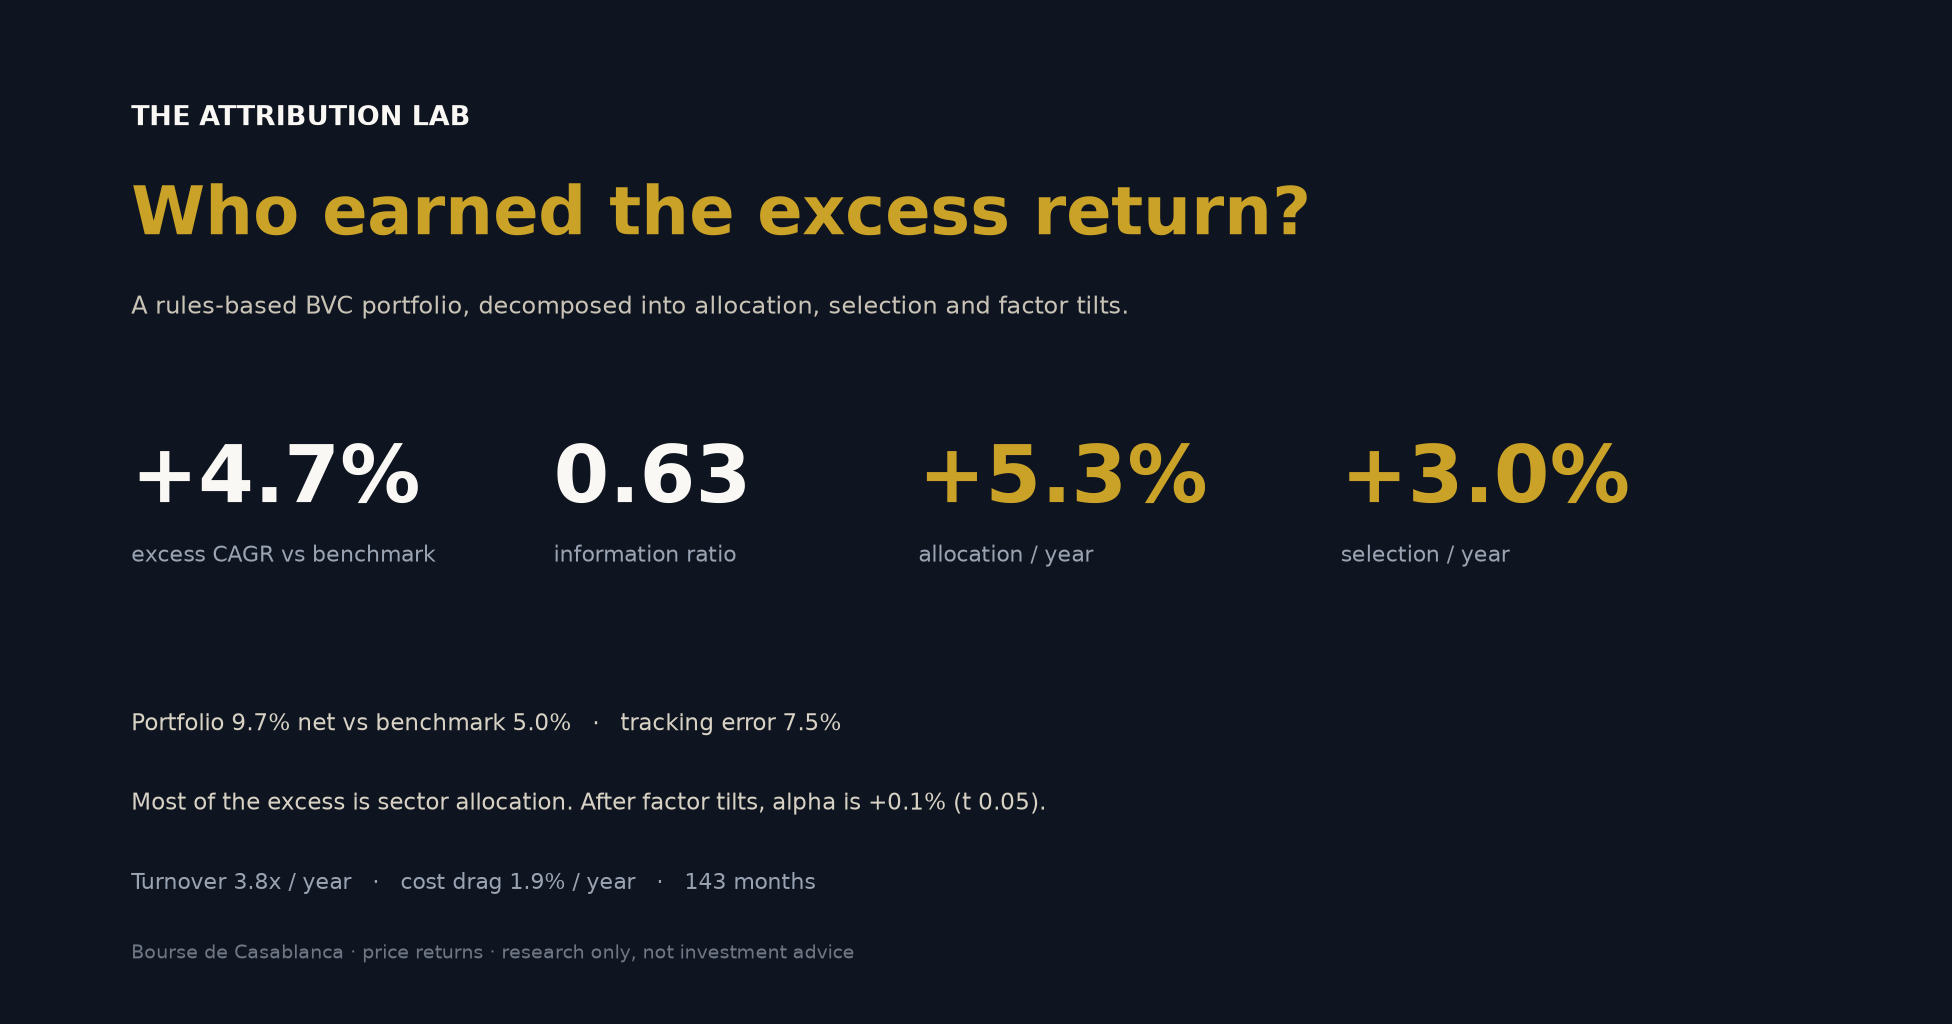
A rules-based 15-name BVC portfolio compounded at 9.7% net against a 5.0% cap-weighted benchmark, a 4.7% annual excess with a 0.63 information ratio. Brinson-Fachler attribution puts 5.3 points on sector allocation and 3.0 on selection, while interaction (-1.7) and costs (-1.9) take back about two-fifths of the gross 8.3. A Newey-West regression on momentum, value, quality, size and low-vol leaves an alpha of +0.1% (t = 0.05). The excess is a systematic sector and factor exposure, not stock-picking skill — and 2024 alone supplies a large share of it.