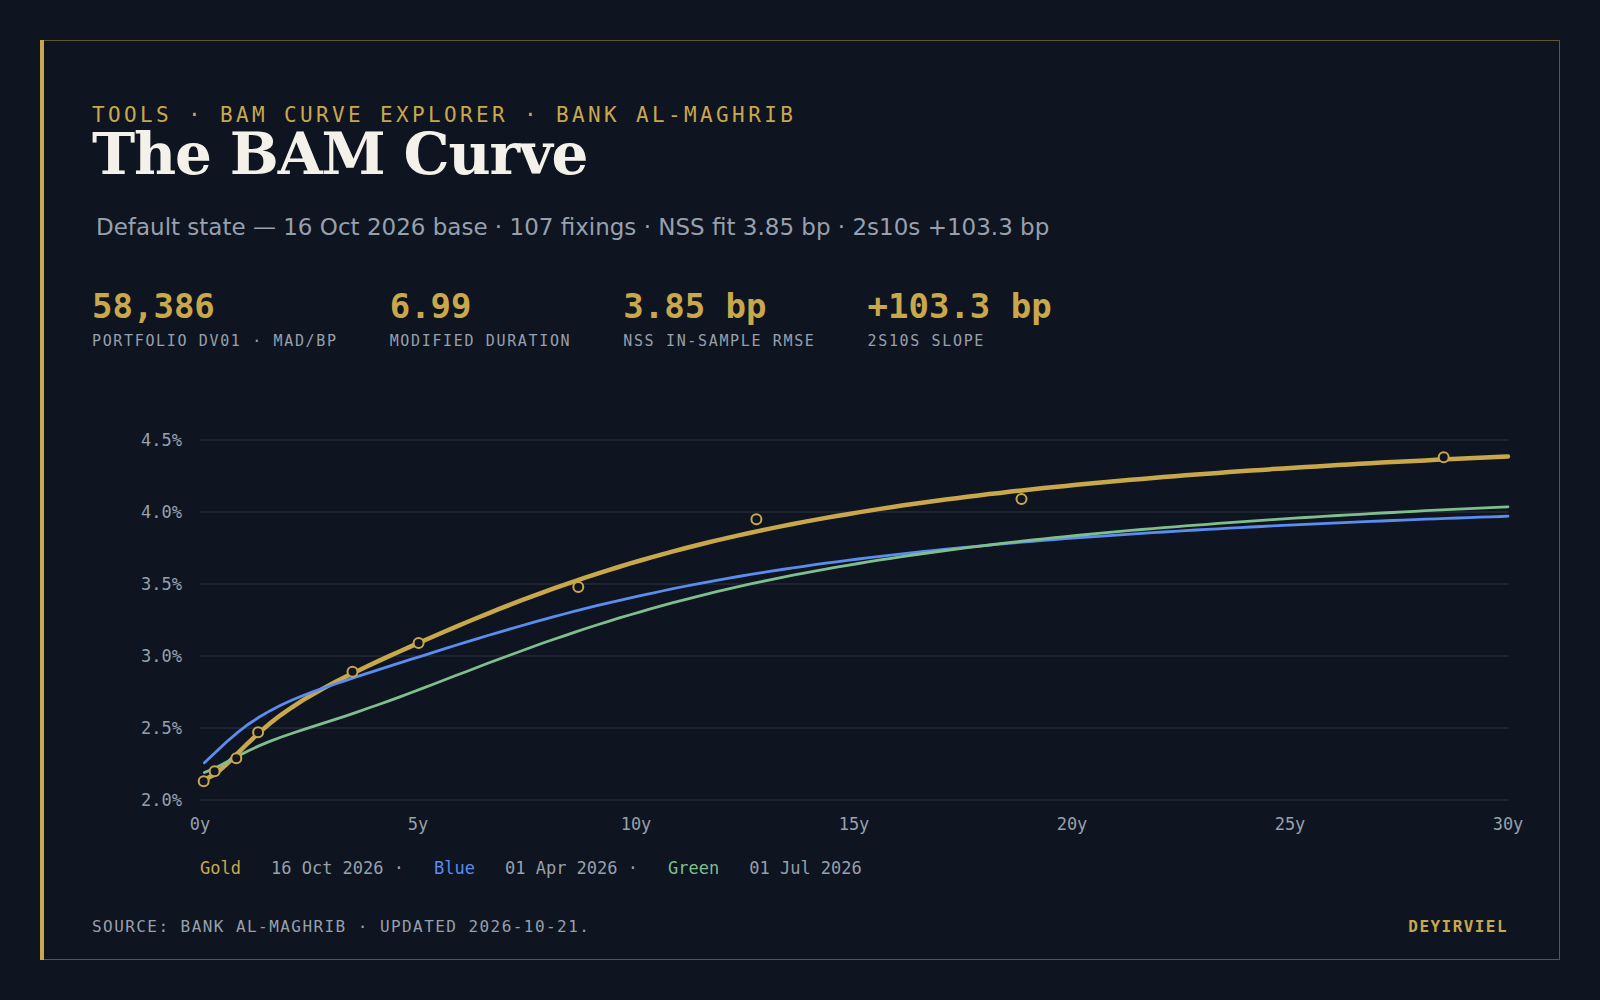
The BAM Curve, Priced and Hedged
Bank Al-Maghrib’s 16 October 2026 reference curve, fitted with NSS (3.85 bp in-sample, 30.6 bp leave-one-out) and used to price an 81.4M MAD sovereign book. A duration-only hedge zeroes total DV01 with a 76.9M short in the 8.7Y line, but concentrates key-rate risk at that point and leaves 3.40B of convexity. A two-instrument duration+convexity hedge zeroes both but leaves +369k to a +100 bp belly move at 12.76Y. A six-line key-rate hedge (3.5Y–28.5Y) cuts belly P&L to +86k, is 95% executable under a 10M-per-line cap, and cuts daily backtest volatility from 112k to 6k MAD. The duration-only hedge leaves 50k and still has the largest residual among the hedges.